
888-529-0707 call 24-7 we service throughout california
Dealing with a Lowball Insurance Settlement Offer in Merced: A Step-by-Step Guide
What if the first settlement offer reflects only the losses an insurer can calculate today, not the treatment and expenses still ahead? If you’re dealing with a lowball insurance settlement offer Merced, it’s understandable to feel pressured to respond before you know whether the amount accounts for your full claim.
A low offer deserves a careful comparison with the facts, not a rushed yes or no. This guide explains how to review an offer against documented medical care, lost income, property damage, and other losses; organize information that may support a response; and identify questions to ask about the insurer’s evaluation. Ongoing negotiations do not necessarily pause a legal deadline to file a lawsuit, so keep any potential deadlines in view.
Law Offices of David Davidi, APLC represents injured people throughout California, including Merced-area clients and people in Los Angeles, Fresno, Modesto, Bakersfield, Stockton, Tulare, Visalia, and Riverside. The firm has 25 years of experience and handles a limited number of cases so an attorney, not an assistant, oversees each case from start to finish. Free consultations are available. No Win No Fee – we work for free, until we win! The firm returns any calls or messages within 24 hours and is available 24/7. SE HABLA ESPAÑOL.
Key Takeaways
- Compare the offer with documented medical expenses, lost income, property damage, and other supported losses rather than judging it by the total alone.
- Separate expenses supported by current records from possible future care or continuing effects that may need more documentation.
- When dealing with a lowball insurance settlement offer merced, save the full offer, review its terms, identify unanswered questions, and keep communications factual and in writing.
- Disputed liability, significant injuries, ongoing treatment, or complicated records may make attorney review helpful before you decide how to respond.
- Law Offices of David Davidi, APLC represents injured clients throughout California, including Merced. An attorney, not an assistant, oversees each case from start to finish. The firm returns any calls or messages within 24 hours. No Win No Fee – we work for free, until we win! SE HABLA ESPAÑOL.
What a Lowball Insurance Settlement Offer Means for a Merced Claim
A low insurance offer can feel like a verdict on what your injuries or losses are worth. It isn’t. An offer may be considered low when it does not appear to account for documented losses and the circumstances of the claim, such as medical expenses, missed work, vehicle damage, or the effect of an injury on daily life. The useful comparison is between the insurer’s reasoning and the available evidence, not simply the offer amount.
That comparison can be difficult when treatment is ongoing, a repair estimate is pending, or you’re waiting for an explanation of how the insurer evaluated the claim. You may feel pressure to respond while these issues remain unsettled. But an opening offer alone does not establish the full value of a claim, and a low offer does not explain by itself how the insurer reached that figure.
An initial offer reflects information considered at that point. It is not necessarily a complete assessment of every documented loss or unresolved claim issue. A settlement is an agreement intended to resolve a legal dispute; the general concept is described in Settlement (litigation). For an insurance claim, review the specific offer and its terms in light of the individual facts.
Why an insurer’s first offer may not answer every claim question
An offer reflects the information available to the insurer when it evaluates the claim. That may include records and estimates already submitted, but it may not address expenses or effects that have not yet been documented. For example, a vehicle repair estimate could be incomplete, or medical records may not yet show the course of ongoing care. These are possible gaps to investigate, not proof that an insurer acted unfairly.
Every claim is different, and not every first offer is intentionally unfair or inadequate. Focus on what the insurer considered and whether its explanation accounts for the evidence you have. If you do not understand how the offer relates to a particular loss, record that as an unanswered question rather than assuming the amount resolves it.
What Merced claimants should understand before deciding
For people dealing with a lowball insurance settlement offer merced, the key is to assess the offer against the facts of their own California claim. A Merced County claimant’s records, injuries, repair needs, and account of the incident may differ substantially from another person’s. There is no reliable shortcut based on location alone, and an offer in one claim does not establish what another claim is worth.
Before deciding how to respond, identify what the offer appears to cover and what remains uncertain. Is there a bill, wage record, repair document, or treatment update that has not been considered? Is the insurer’s view of responsibility consistent with the evidence you have? These questions make a stressful decision easier to organize. The next sections explain how to compare an offer with documented losses and prepare a careful response.
How to Assess a Low Insurance Offer Against Your Documented Losses
Review the offer by checking whether its stated basis accounts for the losses and evidence in your claim. Do not treat the insurer’s total as a complete measure by itself. Separate expenses you can document now from future care or continuing effects that may need more information.
A claim’s value depends on its evidence and individual circumstances, not on a generic average or a number offered before every loss is understood.
Which records can help you review the offer?
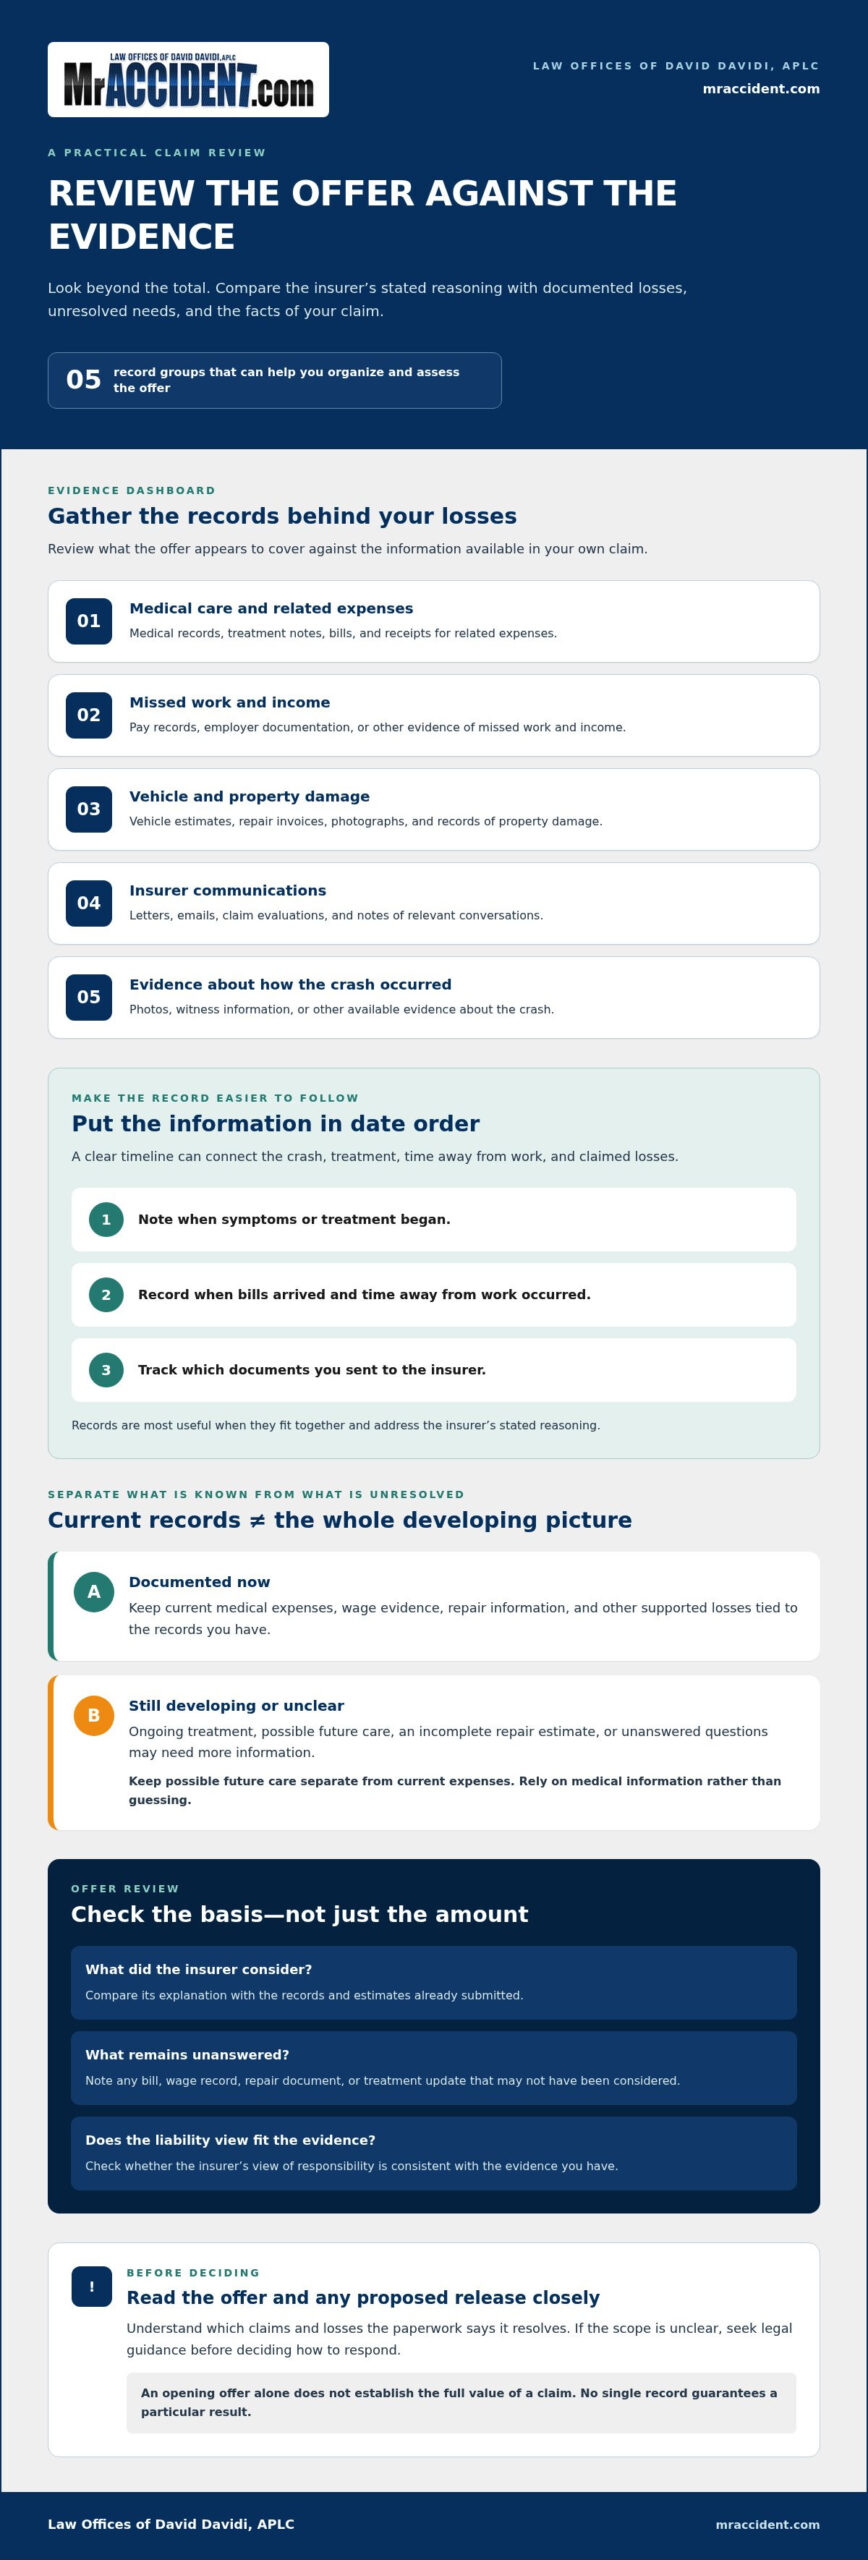
Gather records showing what happened, what care or repairs followed, and how the incident affected your finances and daily life. Useful materials may include:
- Medical records, treatment notes, bills, and receipts for related expenses.
- Pay records, employer documentation, or other evidence of missed work and income.
- Vehicle estimates, repair invoices, photographs, and records of property damage.
- Insurer letters, emails, claim evaluations, and notes of relevant conversations.
- Photos, witness information, or other available evidence about how the crash occurred.
Put these materials in date order. A clear timeline can show the connection between the crash, treatment, time away from work, and claimed losses. Note when symptoms or treatment began, when bills arrived, and which documents you sent to the insurer. No single record guarantees a particular result. Records are most useful when they fit together and address the insurer’s stated reasoning.
How unresolved treatment and future needs affect the decision
If treatment is ongoing or the medical picture is still developing, it may be difficult to understand the full effect of an injury. Keep current expenses separate from possible future care, and rely on medical information rather than guessing about treatment that may be needed. Before responding, read the offer and any proposed release closely. Understand which claims and losses the paperwork says it resolves, and seek legal guidance if its scope is unclear.
Liability evidence matters, too. The insurer may assess responsibility differently based on its interpretation of photos, witness accounts, or other records. In California, pure comparative negligence can reduce compensation according to an injured person’s share of fault, while still allowing recovery when the person is partly responsible. Compare the insurer’s position with the evidence, not just its calculation of expenses.
For people dealing with a lowball insurance settlement offer merced, organizing these records can reveal what is accounted for, what remains uncertain, and what questions to raise. Law Offices of David Davidi, APLC provides car accident legal representation for injured people throughout California, including Merced. The firm has 25 years of experience, handles a limited number of cases, and has an attorney, not an assistant, oversee each case from start to finish. The firm returns any calls or messages within 24 hours. No Win No Fee – we work for free, until we win! SE HABLA ESPAÑOL.
Is the Merced Insurance Offer Too Low? Compare Its Basis, Not Just Its Amount
A quick offer can provide information, but speed alone does not show whether the insurer has completed its evaluation or considered every part of your claim. Compare the insurer’s stated reasons with your records and evidence about how the crash happened. Look for specific gaps, not just a difference between the offer and what you hoped to receive.
Use a comparison like this to organize your review. It will not determine the claim’s value, but it can show what needs clarification or additional support.
| Offer component | Supporting records | Unresolved question | Follow-up action |
|---|---|---|---|
| Medical expenses | Treatment records, bills, receipts | Which visits or charges were considered? | List records sent and identify anything missing. |
| Lost income | Pay records, employer documentation | How did the insurer assess missed work? | Ask which wage information it reviewed. |
| Property damage | Repair estimate, invoice, photographs | Does the evaluation address the documented damage? | Point out any specific difference between the records and evaluation. |
| Liability | Photos, witness details, incident records | What facts support the insurer’s view of responsibility? | Ask for its reasoning and respond with relevant evidence. |
Questions to ask about the insurer’s evaluation
Keep your questions direct and factual. Which records and claimed losses does the offer address? What items were excluded or disputed, and why? Does the insurer need additional documentation to evaluate a particular loss? If its explanation is unclear, request clarification in writing and keep a copy. A specific question tied to a record is more useful than an unsupported demand for a different amount.
For example, if the offer discusses medical bills but does not explain how it considered a wage claim, identify the wage records you provided and ask whether they were reviewed. If the insurer disputes responsibility, compare its explanation with available photos or witness information. Do not assume a discrepancy proves wrongdoing. First establish what evidence each position relies on.
California claim factors that need careful, current review
Liability evidence and applicable California rules can shape settlement discussions, and their effect depends on the facts. The California Department of Insurance provides consumer information, while the California Fair Claims Settlement Practices Regulations address insurance claim handling. For a particular dispute, verify current requirements and how they apply through official California sources or legal guidance. Do not rely on a general summary to determine a deadline or conclude that an insurer violated a rule.
If you’re dealing with a lowball insurance settlement offer merced, use the comparison to separate documented disagreements from unanswered questions. An attorney can assess how the insurer’s reasoning fits the claim evidence and identify issues that may need closer review before you respond.
How to Respond to a Lowball Insurance Settlement Offer
You do not have to answer an offer on the spot. A steady process can help you preserve records, understand what the insurer is proposing, and respond to specific gaps without overstating your claim. Keep the offer and related communications together, and note any date the insurer says applies to its proposal.
- Preserve the offer. Save the full letter or email, including attachments, terms, and any stated response date. Keep message details that show when it arrived.
- Review what it says. Identify what the offer appears to resolve, which losses it addresses, and whether it includes a release or other paperwork. Do not assume the amount alone explains the insurer’s evaluation.
- Gather relevant records. Collect the medical, wage, repair, and incident records tied to the disputed points. A well-organized timeline can connect the crash with treatment, missed work, and expenses.
- Identify gaps. Note which documented losses appear unaddressed, which records may be missing, and where the insurer’s explanation is unclear.
- Plan a factual response. Address each disputed loss or fact separately. Refer to supporting records, attach copies where appropriate, and ask a clear question if you need the insurer to explain its reasoning.
Keep communications calm, accurate, and in writing whenever practical. Save copies of letters, emails, documents sent, and responses received. Avoid guessing about future expenses or making claims you cannot support. A counterresponse should show how the evidence relates to the issue, not rely on a formula or assume the insurer will increase its offer.
Build a clear, evidence-supported counterresponse
Organize your response around the insurer’s specific evaluation. For example, if a wage loss is disputed, identify the relevant wage documentation and ask what additional information is needed. If the insurer’s view of liability is unclear, request its explanation and compare it with the available evidence. A direct, documented response makes the disagreement easier to understand, though it cannot guarantee a different offer.
When to pause before accepting or signing
Unresolved treatment, missing records, or unclear release language can make it harder to understand what you’re agreeing to. A release may affect the claims described in its terms, but its scope and consequences depend on the document and circumstances. Read it carefully and seek legal guidance if you’re unsure. Check any response date in the offer promptly. Do not assume there is one universal deadline. General settlement discussions also cannot establish what your individual claim is worth, a point to keep in mind when considering settlement information.
Law Offices of David Davidi, APLC offers free consultations for injured people throughout California, including Merced. The firm has 25 years of experience, handles a limited number of cases, and an attorney, not an assistant, oversees each case from start to finish. Request attorney guidance on your settlement offer. The firm returns any calls or messages within 24 hours. SE HABLA ESPAÑOL.
When Merced Drivers Should Get Attorney Help With a Low Offer
Attorney review may be useful when the insurer disputes who caused the crash, your injuries are significant, treatment is continuing, or the claim involves records that are difficult to interpret. These factors can make it harder to tell whether an offer addresses the evidence and the full circumstances of your claim. You do not have to guess what the insurer’s position means or work through every question alone.
Consider getting guidance if the insurer’s explanation conflicts with records you have, important losses appear unaddressed, or you’re uncertain about the effect of signing settlement paperwork. A careful review can help clarify which questions remain and what options may be available. It cannot guarantee a particular outcome, but it can give you a clearer basis for deciding how to proceed.
What attorney-led claim review can help clarify
An attorney can review the offer alongside supporting records, the insurer’s explanation, and evidence related to liability. That review may help identify disputed facts, documentation gaps, or terms that deserve closer attention. It can also help you prepare focused questions and consider possible next steps based on your situation, rather than relying on a generic estimate or negotiation formula.
For background on how legal advocacy may relate to a car accident claim, see Car Accident Attorney: Secure Maximum Compensation with Expert Legal Advocacy. Law Offices of David Davidi, APLC represents injured people throughout California, including Merced-area clients. The firm has 25 years of experience, handles only a limited number of cases, and ensures an attorney, not an assistant, oversees each case from start to finish.
The firm provides car accident representation on a No Win No Fee basis: A free consultation gives you the opportunity to discuss the offer, the evidence you have, and questions about your next steps without assuming any result is assured.
A clear next step for Merced-area claimants
If you’re dealing with a lowball insurance settlement offer merced, gather the offer, related correspondence, and records that support your claimed losses before discussing your circumstances. These materials give the attorney a practical starting point for reviewing what the insurer considered and what remains in dispute. You can discuss the terms, supporting evidence, and decisions you may need to make.
Law Offices of David Davidi, APLC serves injured clients throughout California, including Merced, Los Angeles, Fresno, Modesto, Bakersfield, Stockton, Tulare, Visalia, and Riverside. The firm is available 24/7, offers free consultations, and returns any calls or messages within 24 hours. An attorney, not an assistant, oversees each case from start to finish. SE HABLA ESPAÑOL.
Take Your Next Step With Clarity
You do not have to make a difficult decision simply because an offer has arrived. Take time to understand what remains uncertain, identify the questions you want answered, and choose a next step that fits your circumstances. A careful review can help you move forward with a clearer understanding of the claim, even when the issues feel complicated.
If dealing with a lowball insurance settlement offer merced has left you unsure what to do, discuss the offer and your concerns with the Law Offices of David Davidi, APLC. The firm represents injured people throughout California, including Merced-area clients, and an attorney, not an assistant, oversees each case from start to finish.
Request a free consultation about your settlement offer. Call 888‑529‑0707 or 888‑LAW‑0707. SE HABLA ESPAÑOL.
Frequently Asked Questions
Can I reject a low insurance settlement offer in California?
Yes, you can choose not to accept an offer. If you’re dealing with a lowball insurance settlement offer merced, first review the proposal for its terms, conditions, and any stated response date. You can ask the insurer to explain how it evaluated your claim and keep a record of your request and its response. The effect of declining depends on the specific offer and claim circumstances, so consider legal review if important terms or disputes are unclear.
What happens if I sign an insurance settlement release?
A signed release may resolve the claims covered by its language, so read the whole document before signing. Pay attention to which parties and claims it identifies and whether it describes the settlement as final. Do not assume you can reopen a claim later. Whether that may be possible depends on the release and circumstances. Keep a complete copy, including attachments, and seek an attorney’s review if the wording does not match your understanding of the agreement.
How long do I have to respond to an insurance settlement offer?
There is no response period that safely applies to every offer. Check the letter or email for a requested date, and promptly ask the insurer in writing to clarify any unclear timing. Keep that date separate from any legal deadline that may apply to filing a claim or lawsuit. If you’re unsure which deadlines affect your situation, get advice based on the incident date, claim type, and current California law.
Can an insurance company withdraw a settlement offer?
It may depend on the offer’s wording, whether it was accepted, and the surrounding circumstances. Save the written offer and any messages that discuss changes, and make a dated note of relevant phone calls. If the insurer withdraws or revises its proposal, ask it to explain its position in writing. An attorney can review the offer, your communications, and the timeline to help you understand what the change may mean for your claim.
Should I accept an offer while I am still receiving medical treatment?
Be cautious about deciding while treatment is ongoing, because your medical records and understanding of your needs may still be developing. Review the proposed release to see which claims it addresses, and do not assume future care is either included or excluded without reading the specific terms. For example, consider how the document treats injury-related claims if your treatment plan changes. An attorney can help assess unresolved treatment and release language before you sign.
Does refusing an insurance offer mean my car accident case will go to trial?
No. Declining an offer does not by itself mean the case will go to trial. The parties may continue discussions, exchange information, or consider other available steps, depending on the facts and circumstances. Neither a settlement nor a trial is certain just because you reject a proposal. Before choosing how to respond, consider what evidence remains to be reviewed and ask an attorney to explain possible paths for your particular claim.
Can I ask the insurance adjuster to explain a low settlement offer?
Yes. You can request a written explanation identifying which records and claimed losses the adjuster considered and what information may be missing. Keep the request concise and factual with your claim documents. For broader property damage claims, advocacy resources like donnauro.com offer insight into how public adjusters document and negotiate property insurance settlements. If your crash happened in Merced, Los Angeles, Fresno, Modesto, Bakersfield, Stockton, Tulare, Visalia, or Riverside, organize the same core materials: the offer, relevant records, and the questions you need answered. A request may clarify the evaluation, but it does not guarantee a changed offer.

Law Offices of David Davidi, APLC is a California – based Personal Injury Law Firm, our Attorney’s provide the representation for your personal injury, accident, product liability, premises liability, and other
negligence resulting in injuries. We treat all clients and cases, large or small, with hands-on care.
Practice Area
© Copyright 2026 Law Offices of David Davidi, APLC. All rights reserved.
Digital Marketing By 